See the Full Cost Before You Borrow
Greenville business funding broker. SBA loans, credit lines, equipment and cash advances, compared in plain dollars.
- 30 plus lendersbanks, SBA lenders and funders
- Soft pull firstno hit to your score to look
- Fee in writingbefore you sign anything
- Evans Street officesit down with a person
Which Funding Fits Your Business?
Answer five questions. You get the options that tend to fit, with typical terms. It is a guide, not an approval.
Your Likely Options
Best fit first. Rates are sample ranges, not quotes.
What a Cash Advance Really Costs
A merchant cash advance is not a loan. A funder buys part of your future sales and takes a cut every business day. The price is a factor rate, not an interest rate.
The total cost can be high. This is a sample only, not an offer. Real factor rates depend on your sales, your bank statements and the funder. A line of credit or term loan usually costs far less, if you can qualify.
What Greenville Businesses Borrow For
The right money depends on what it buys. Here is what we match most often.
Equipment Financing
Tractors, trucks, ovens, lifts. The equipment backs the loan, so the rate is often lower. Terms of two to seven years.
Lines of Credit
Draw what you need for stock or payroll, pay it back, draw again. You pay interest only on what you use.
SBA Loans for Expansion
The SBA 7(a) and 504 programs carry long terms and lower payments. They take longer and ask for more paperwork. Worth it for a buildout, a second spot or a building.
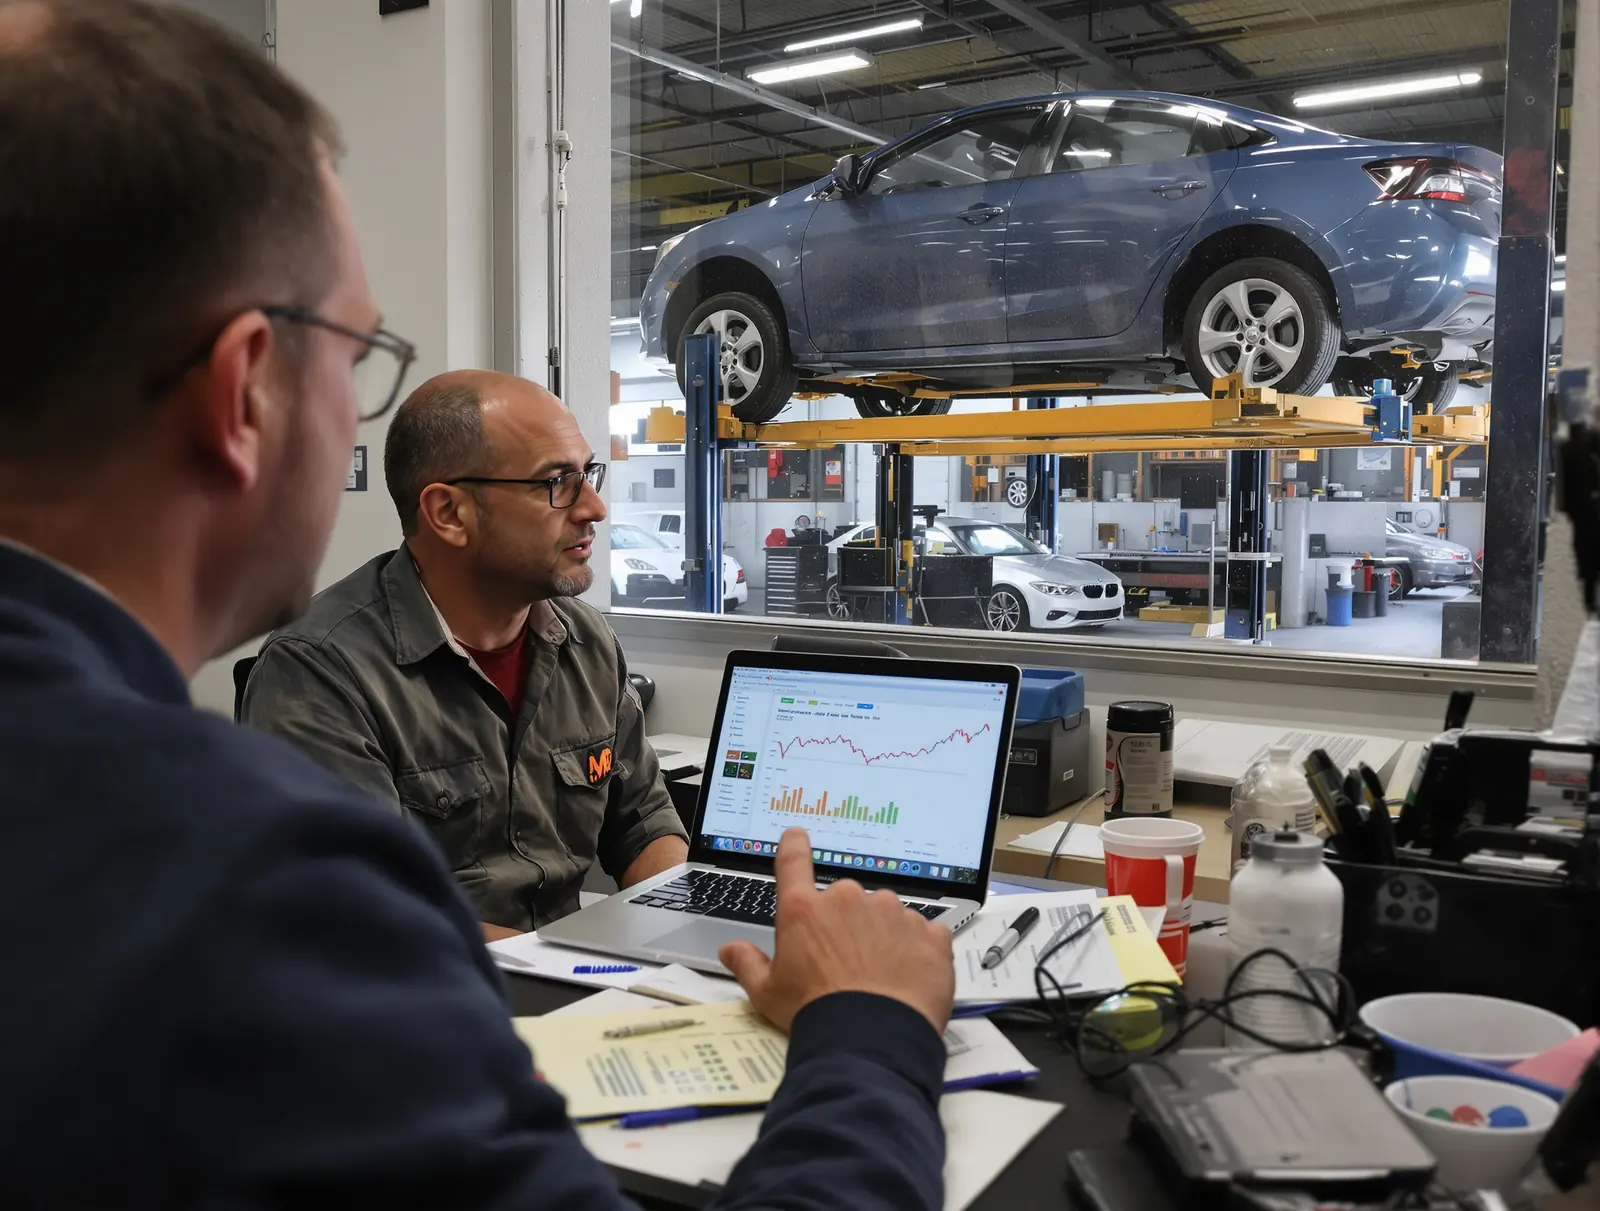
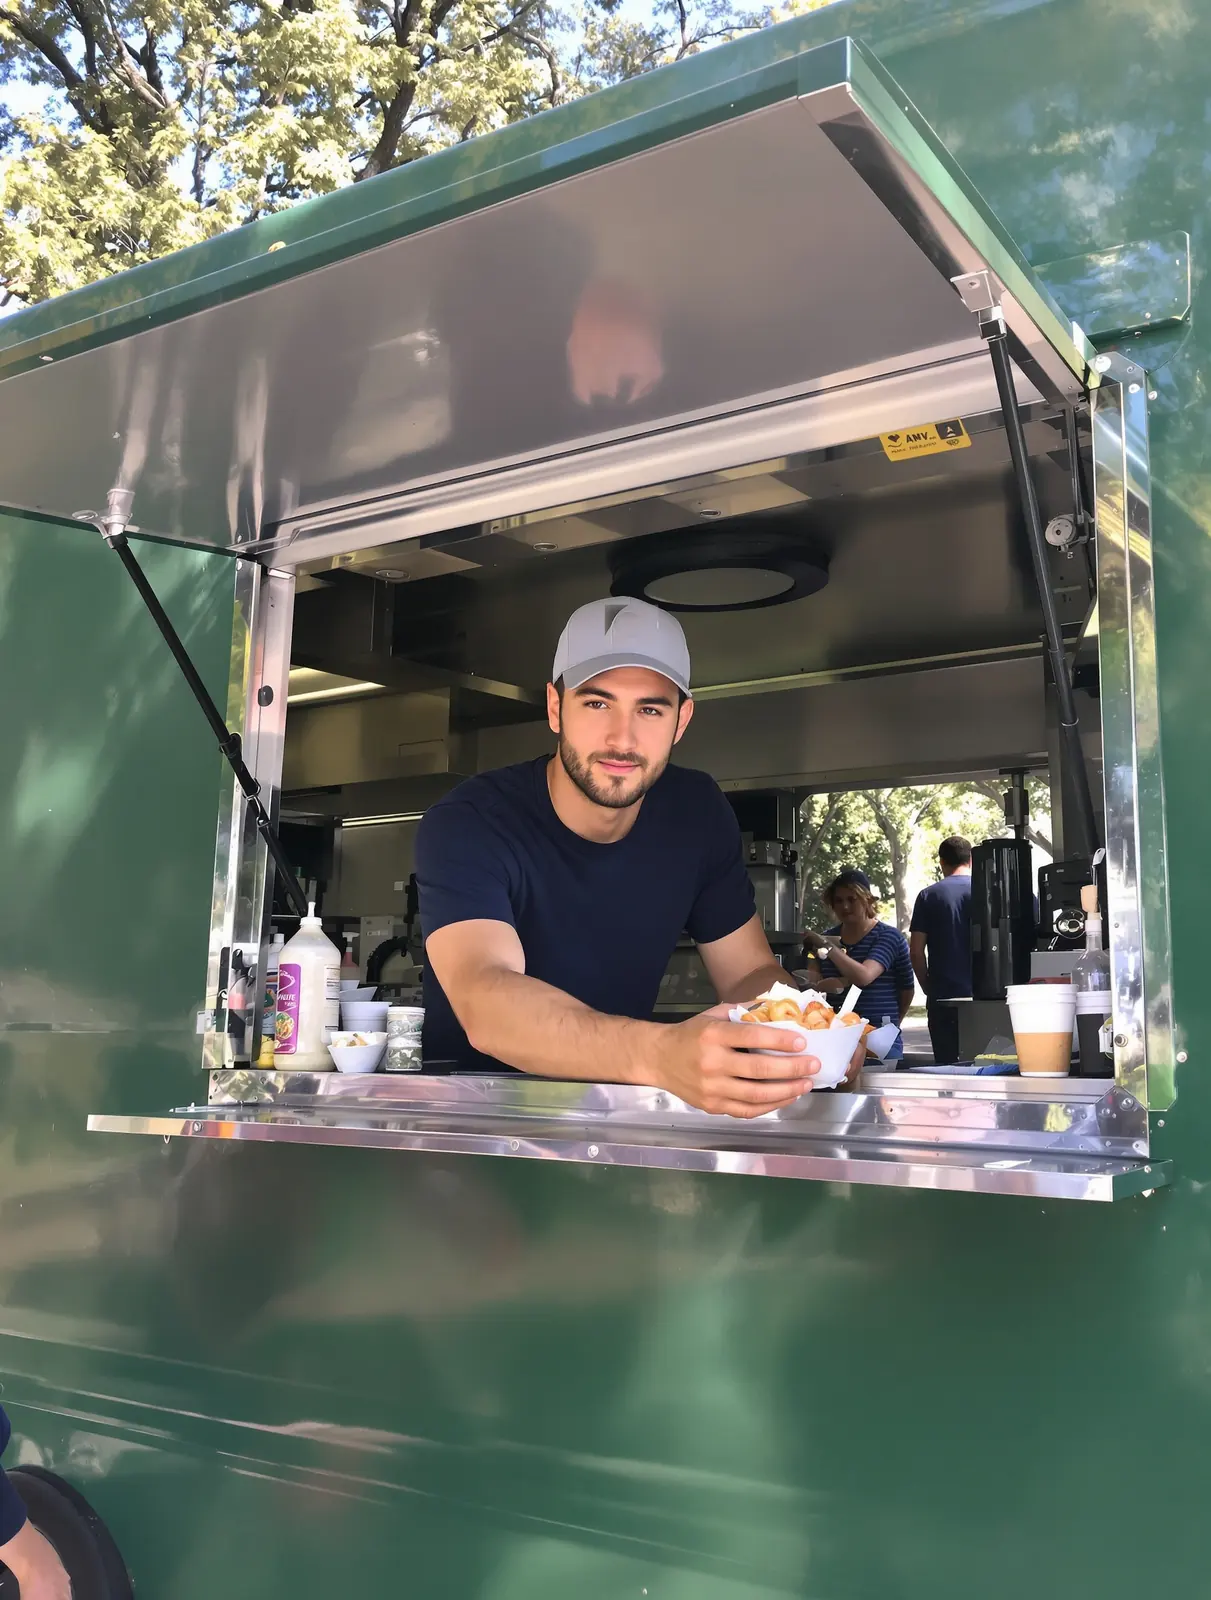
We Come to Your Shop
Most of our clients never sit in our office. We meet at the counter, in the kitchen or at the truck, and bring every offer printed side by side.
- Every offer in dollarsPayment, term, total payback and every fee, on one sheet.
- Our fee on paper firstYou know what we earn before you sign.
- A straight no when it fitsIf waiting three months gets you a better loan, we say so.
What Owners Say
They talked me out of a cash advance and into an equipment loan. My payment is about half what the advance would have cost.
Marcus T. Winterville
The SBA loan took ten weeks, and Dana warned me it would. She kept the paperwork moving the whole time.
Priya S. Greenville
Every offer was on one sheet with the total payback in big numbers. First time I actually understood what I was signing.
Lonnie H. Farmville
Sample reviews written for this demo. Your site shows your real Google reviews, word for word.
Serving Eastern North Carolina
From our office on Evans Street, we work with businesses across Pitt County and the towns around it.
Questions Owners Ask First
Are you a lender?
No. We are a broker. We look at your business, then send it to the lenders that fit. You see every offer side by side, and you pick. If no offer makes sense, we tell you that too.
How do you get paid?
The lender pays us a fee when a deal closes. We tell you the amount in writing before you sign. There is no fee to talk or to see offers.
Will checking my options hurt my credit?
The first look uses a soft pull, which does not touch your score. A lender will do a hard pull only after you choose to apply with them.
What do I need to apply?
Most lenders ask for three to six months of bank statements, your last tax return and a photo ID. SBA loans ask for more, like two years of returns and a debt list. We send you the exact list for each option.
Is a cash advance a bad idea?
Not always, but it is often the most expensive money a business can get. It can make sense for a short gap with a clear payback, like a big order you already have. We show the total payback in dollars before you decide.
Talk It Through First
Leave a first name and a number. We call back the same business day.