From our kitchen table to yours
Bring the Whole Family. We Mean It.
A reverse mortgage touches everyone who loves the house. So we ask your kids to sit in, we answer the hard questions first, and we tell you when it is the wrong move.
Frank and Mariana LuceroFather and daughter, sample owners of this demo office
What Every Reverse Mortgage Asks of You
These come with every . We say them before anything else.
- Counseling comes firstYou meet with a HUD approved counselor who does not work for us, before you can apply. We hand you a list of agencies and you pick one.
- You keep paying the house billsProperty taxes, homeowners insurance, HOA dues and upkeep stay yours. Falling behind can cause the loan to come due.
- It comes due when the last borrower leavesWhen the last borrower sells, moves out for good or passes away, the loan is repaid. Most families sell the house or refinance. It is a loan.
The Family Meeting Checklist
Go through this together before you call anyone, us included. Pick Yes, Not sure or No for each line. The panel tells you what to sort out first. We filled in three lines as an example. Nothing leaves this page.
What Families Use It For
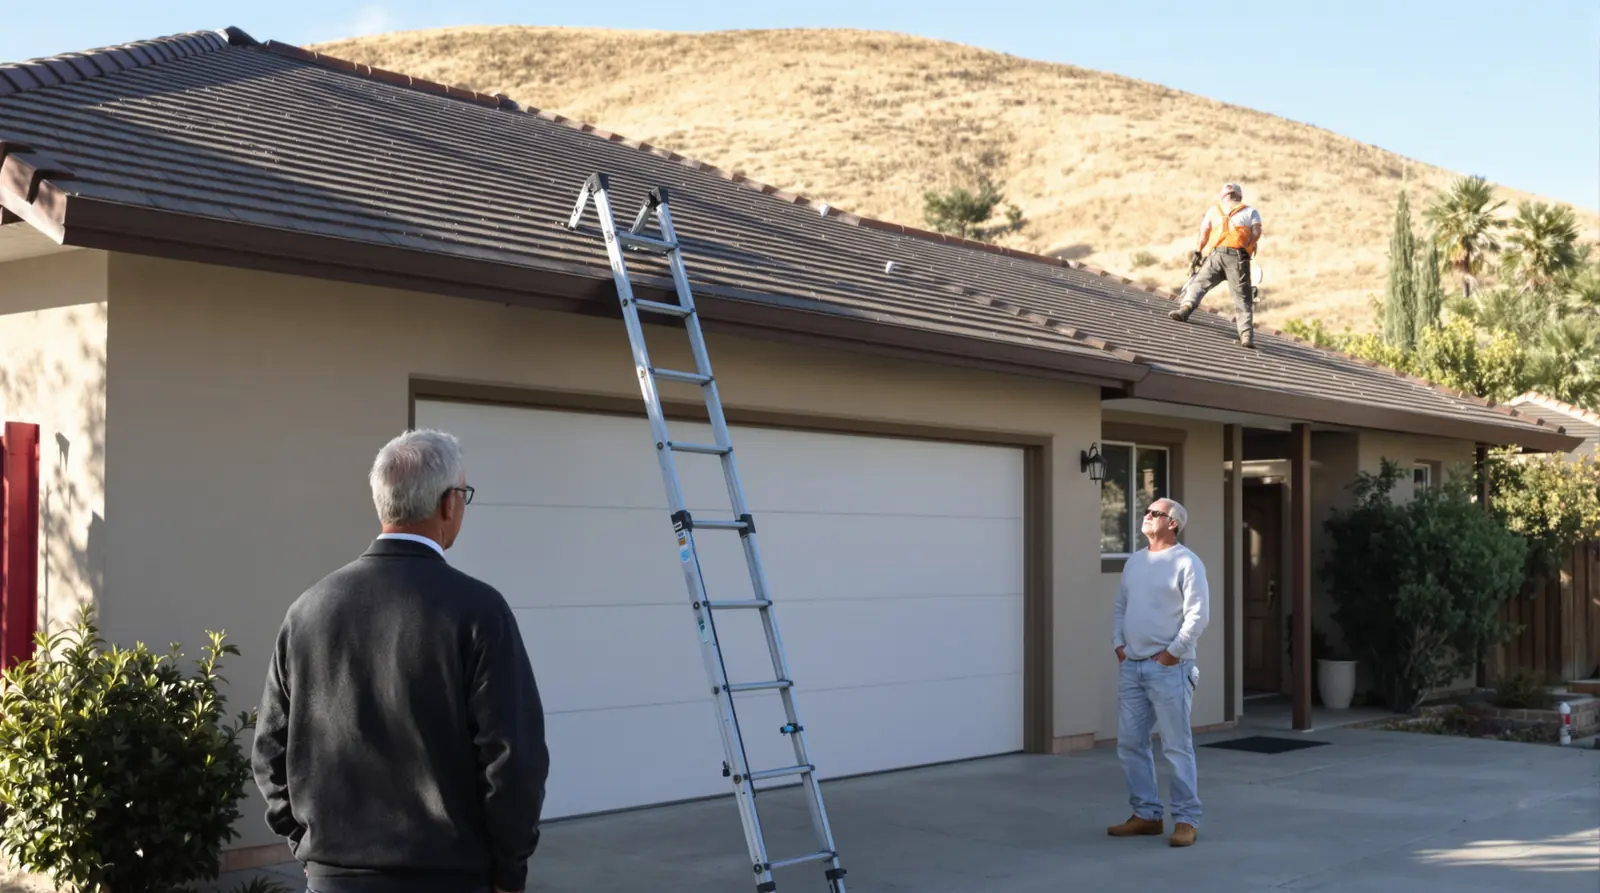
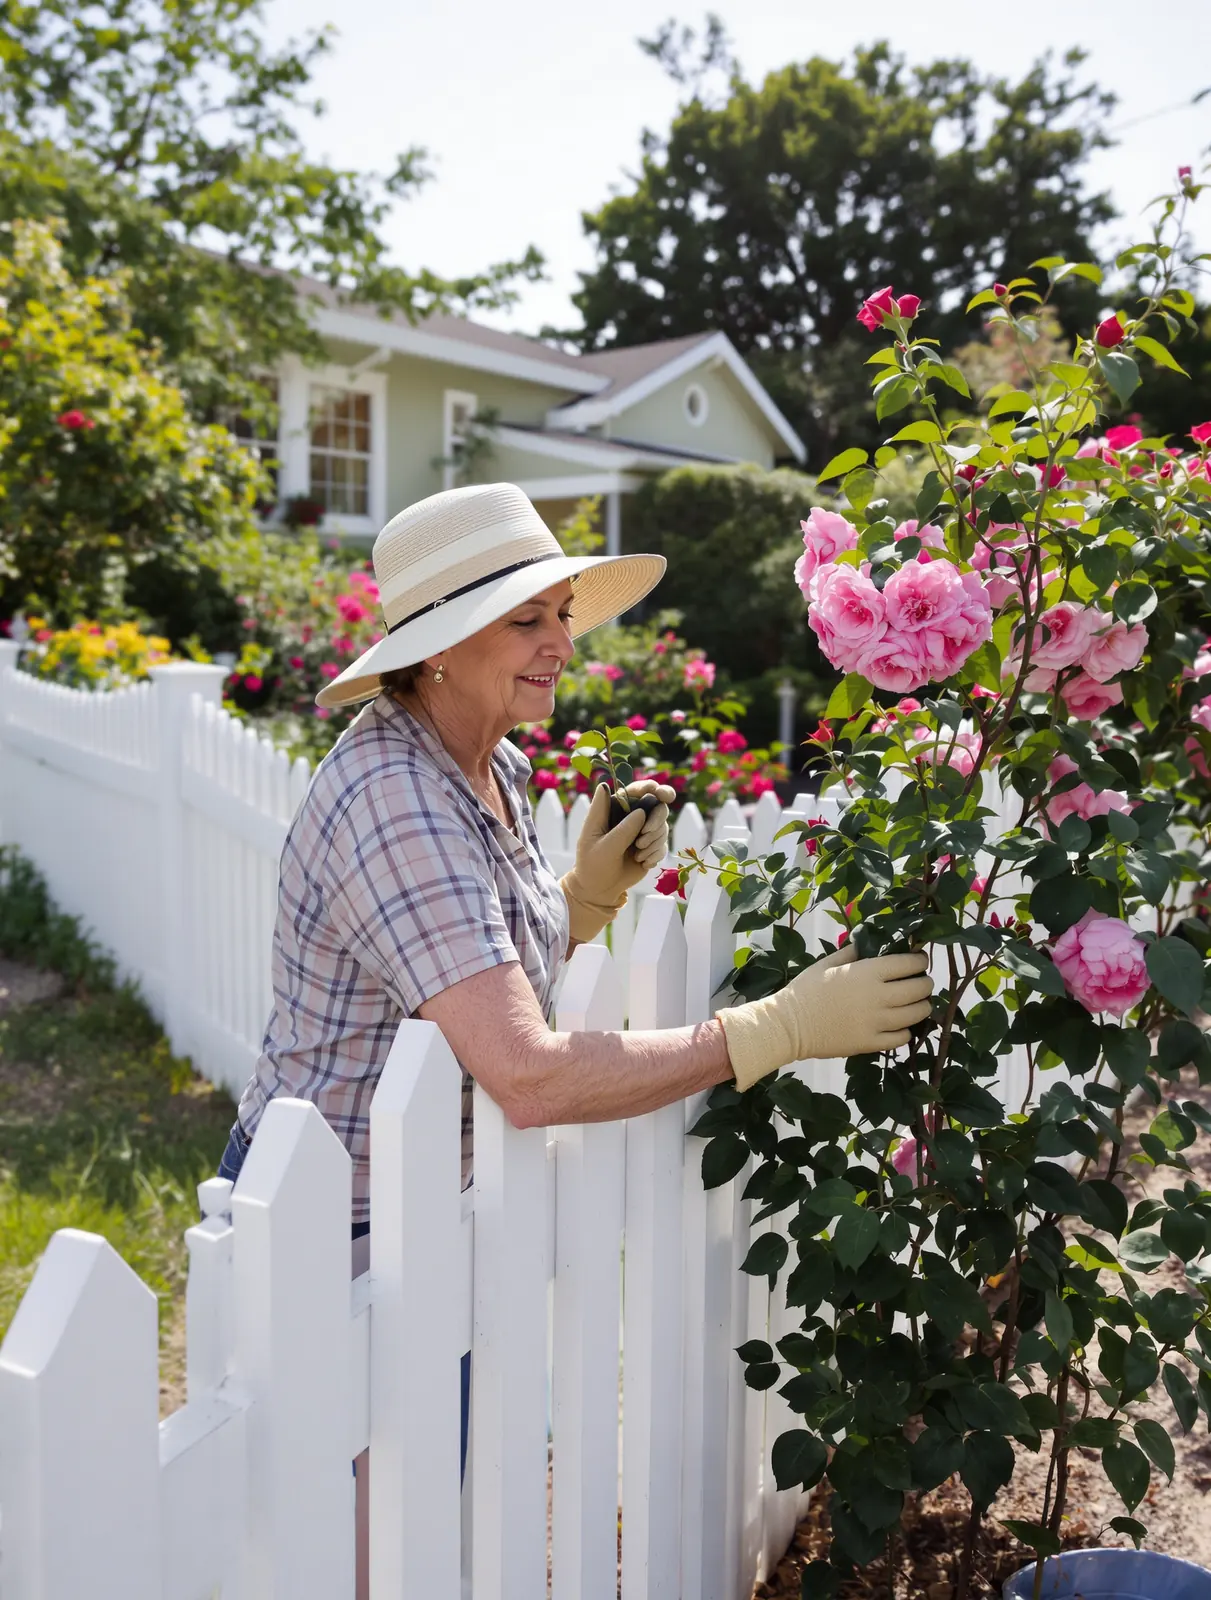
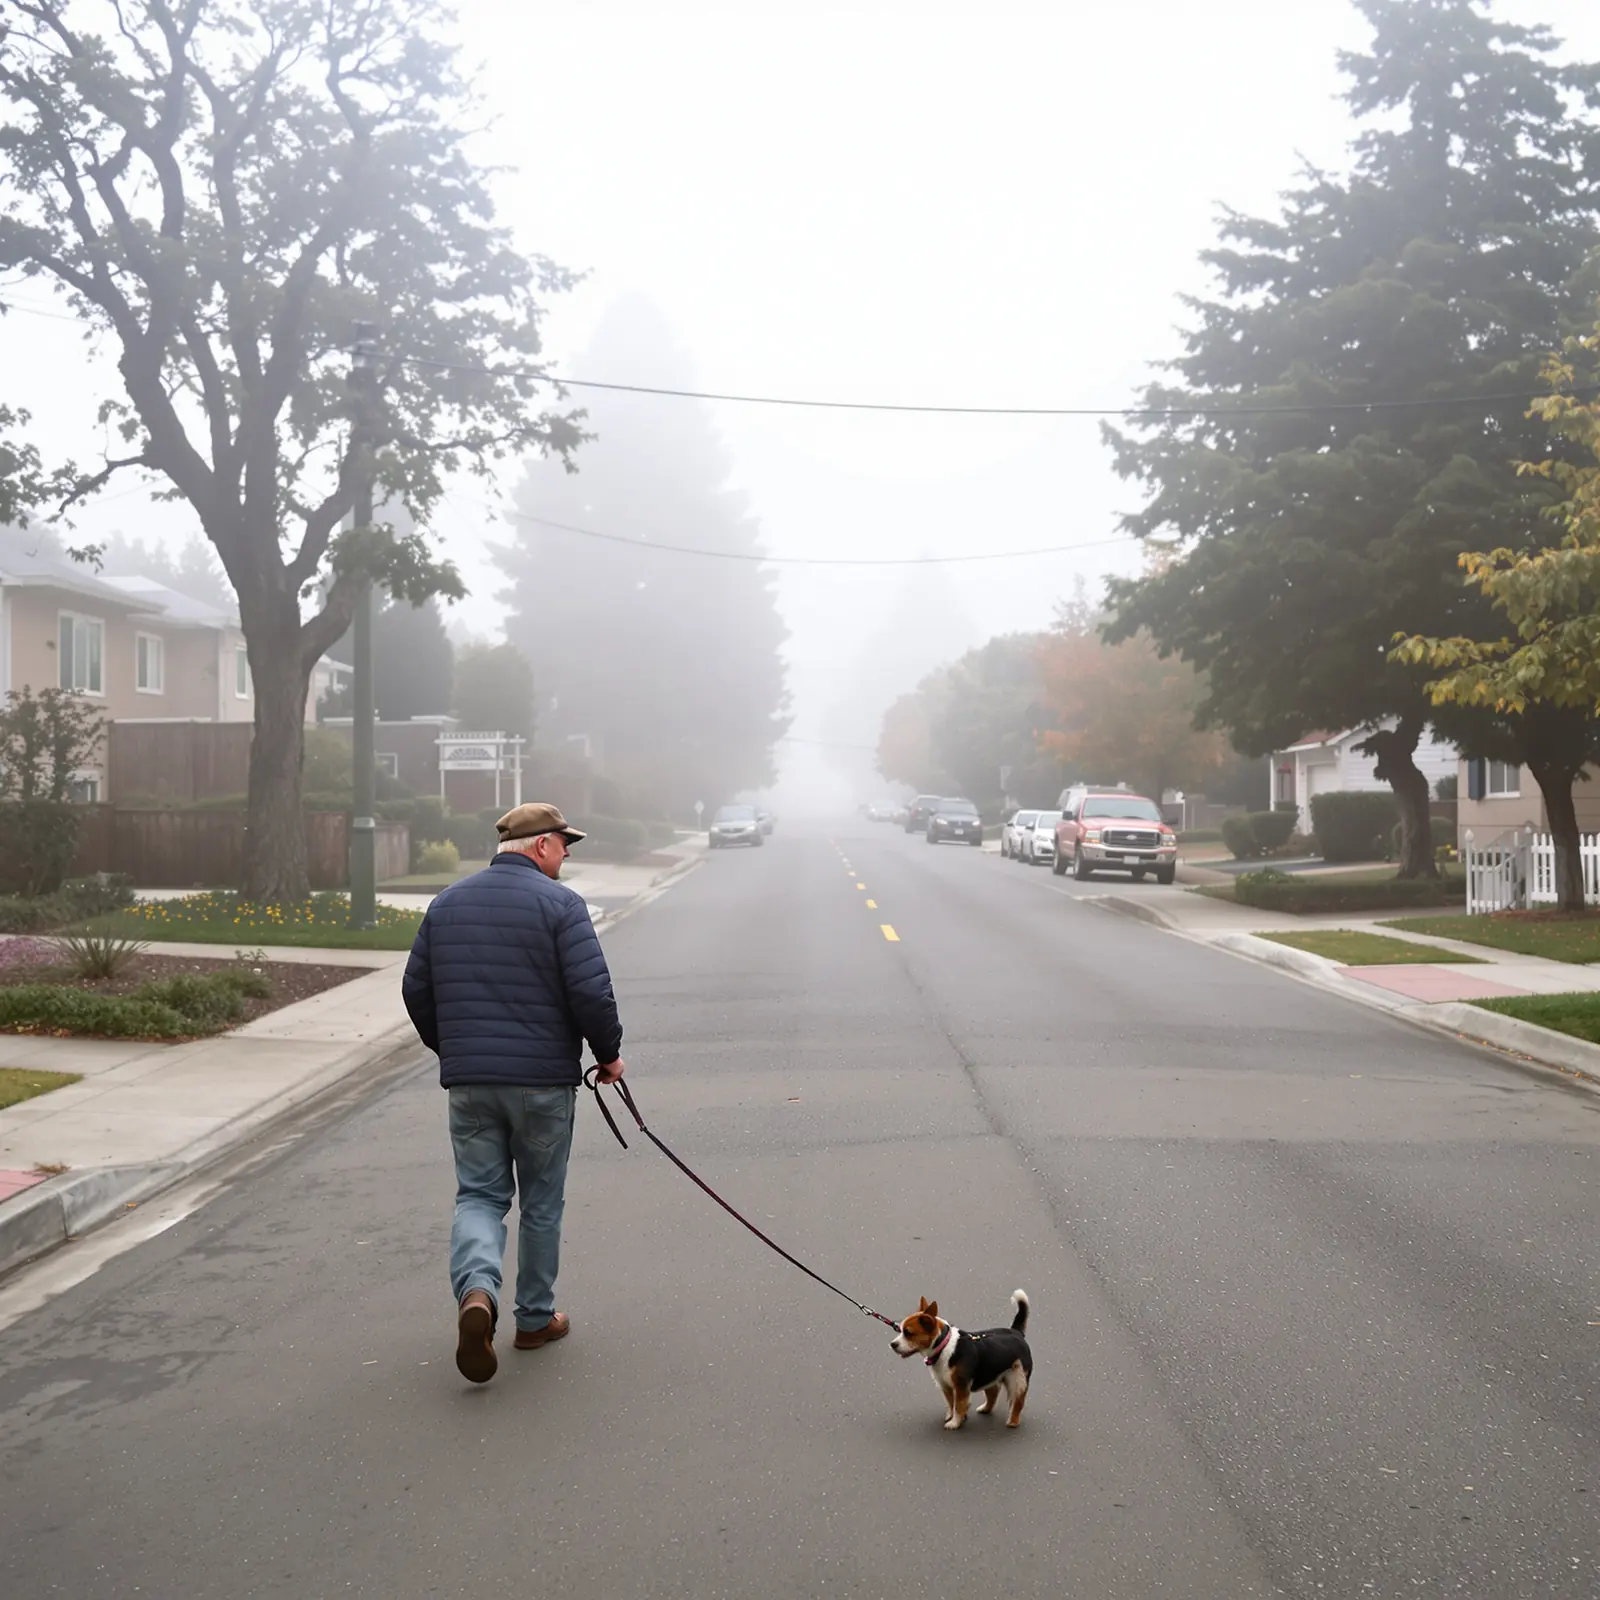
Nobody calls us to get rich. They call to stay home. Tap a photo to see it bigger.
A Family Office, on Purpose
Frank started lending in Sonoma County in 1998. Mariana joined after helping her own grandmother through a reverse mortgage. Between them they have sat at a lot of kitchen tables.
- Open
- Weekdays 9 to 5, home visits by appointment
- Office
- 400 Sample Lane, Santa Rosa
- Languages
- English and Spanish
- Cost to meet
- Nothing, and no pressure to sign
What Families Say
4.9★★★★★118 Google reviewsMariana asked my brother and me to come to every meeting. When Mom passed, we already knew what to do.
Teresa G. Petaluma
Frank told us our taxes were the real issue and set money aside for them. We sleep better.
Walt and June H. Sebastopol
They said it was not right for us and suggested we downsize. Honest people.
Ron P. Rohnert Park
Sample reviews written for this demo. Your site shows your real Google reviews, word for word.
Questions Families Ask
The ones we hear at nearly every kitchen table.
Santa Rosa, Rohnert Park, Petaluma, Sebastopol, Windsor, Healdsburg, Sonoma and Cotati. Phone and video anywhere in California.
Will we lose the house?
You keep the title. The loan can come due early if you stop paying property taxes or insurance, let the house fall apart, or move out for more than twelve months in a row. We check that those bills fit your budget before anything else.
What happens when Dad passes away?
The loan comes due when the last borrower leaves the home. The family can sell the house and keep what is left, pay off the loan, or refinance. With a HECM, the family never owes more than the home is worth when it sells.
Why do we need counseling?
Every HECM requires a session with a HUD approved counselor who does not work for us. It takes about an hour, by phone or in person, and costs about $125 to $200. The counselor goes over costs and other options. We give you a list of agencies to choose from.
Can Mom stay if she is younger and not on the loan?
Often, yes. A spouse under 62 can be named as an eligible non borrowing spouse and stay in the home after the borrower dies, as long as the rules are met. She cannot draw more money from the loan. We go through it with both of you.
What does it cost?
There is an upfront mortgage insurance premium, closing costs and an origination fee, and most of it can come out of the loan. Interest and insurance add to the balance over time. We put every cost in writing before you decide.